Home insurance for older homes in Ohio: why it's more complicated
If you own an older home in Ohio, you already know what comes with it. Wide plank floors, solid plaster walls, detailed woodwork, and a neighborhood with actual character. But when it comes to home insurance for older homes in Ohio , that character introduces coverage questions that don't apply to a house built last decade. Carriers look at older homes differently, underwriters ask more questions, and the cost to properly insure one is rarely straightforward. Understanding why makes a real difference when you're shopping for coverage or reviewing what you already have.
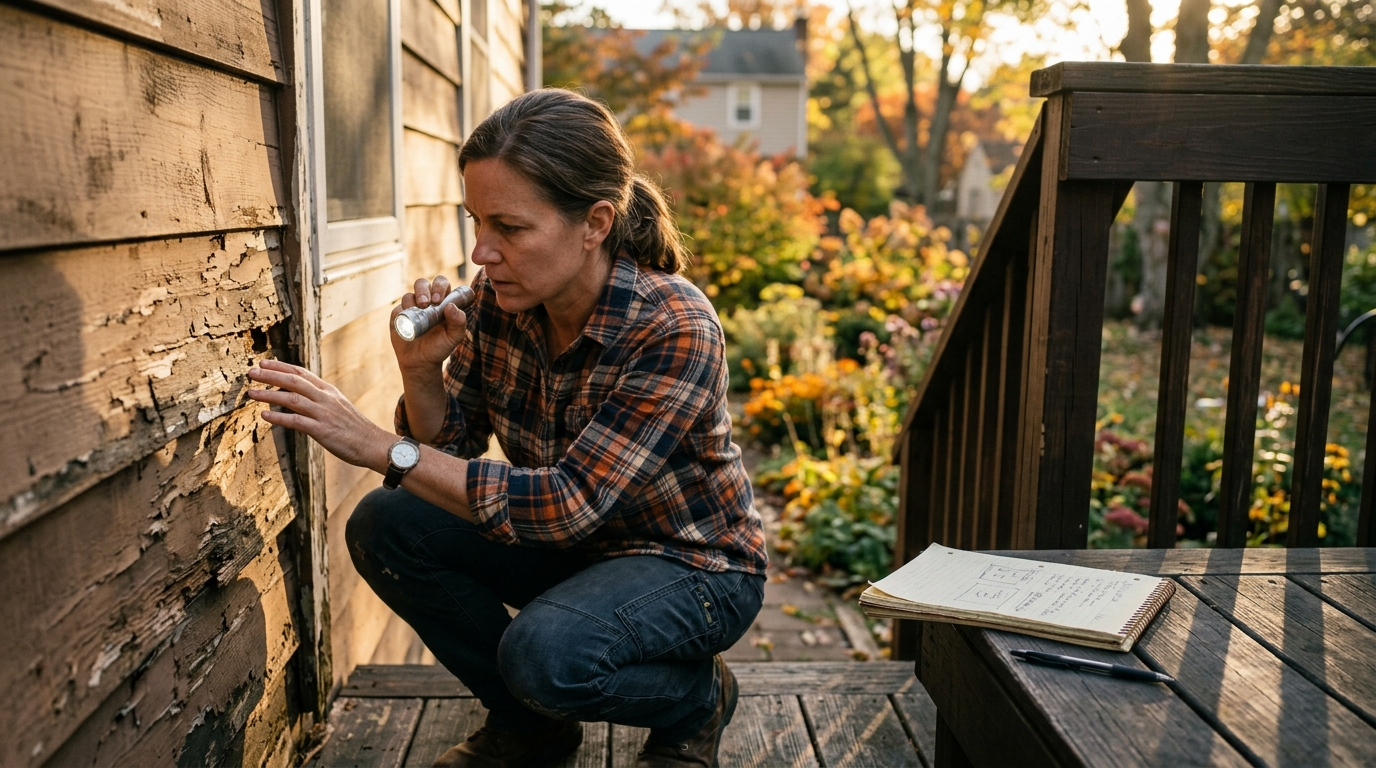
What insurers look at when rating an older home
A home built in the 1920s, 1940s, or even the 1970s carries risks that a newer home simply doesn't. Underwriters aren't trying to be difficult. They're accounting for real cost drivers that show up in claims. The main factors they evaluate:
- Roof age and material. An original slate or wood shake roof is expensive to repair and difficult to match. Standard carriers may require a roof inspection or decline coverage altogether if the roof is over 20 years old.
- Electrical systems. Knob-and-tube wiring (common in homes built before 1950) and fuse-box panels are fire hazards. Many carriers in Ohio won't write a policy on a home with knob-and-tube unless it has been fully replaced. Aluminum wiring from the 1960s and 70s creates a similar problem.
- Plumbing. Lead pipes, galvanized steel lines, and cast iron drains corrode over time. Carriers want to know the pipe material and condition because water damage is one of the most frequent and expensive claims.
- Foundation type. Stone or brick foundations common in pre-war Ohio homes settle differently than poured concrete. Cracks, moisture intrusion, and structural shifting affect both underwriting and replacement cost.
- Replacement cost vs. market value. This is where many older-home owners get caught off guard. The cost to rebuild a 1930s craftsman bungalow with period-appropriate materials can be two or three times its market value. If your coverage limit is set at market value, you're underinsured.
The replacement cost problem with older Ohio homes
This deserves its own section because it's the most common mistake older-home owners make. Replacement cost is what it costs to rebuild your home to the same quality and square footage using today's labor and materials, not what you paid for it and not what it would sell for today.
Older homes in cities like Lima, Findlay, Defiance, and Piqua often sell for $80,000 to $150,000. But the cost to rebuild that same 1,800-square-foot, two-story Victorian with real wood millwork, plaster walls, hardwood floors, and a wraparound porch could easily run $300,000 or more. If your policy limit is tied to purchase price or current market value, a total loss would leave you far short of what you need to actually rebuild.
Ask your agent to run a replacement cost estimator specifically designed for older construction. This is different from the standard calculator carriers use for new builds. The numbers will likely surprise you, but knowing them protects you.
Some carriers offer an extended replacement cost endorsement that adds 20-50% above your stated limit if construction costs spike after a major loss. For older homes, this buffer is worth serious consideration. You can read more about how coverage limits and deductibles interact in our post on understanding essential home and auto insurance coverages.
Knob-and-tube wiring and other deal-breakers
Some issues make an older home difficult or expensive to insure at all.
Knob-and-tube wiring
If your home was built before roughly 1950, there's a real chance it still has original knob-and-tube wiring in some areas, even if the main panel has been updated. This wiring lacks a ground wire, generates more heat, and deteriorates with age. Most standard carriers in Ohio will decline to write the policy or require full replacement before binding coverage. Some specialty markets will write it with a surcharge and limitations on coverage.
Federal Pacific and Zinsco panels
These panel brands, common in homes from the 1950s through the 1980s, have documented issues with breakers failing to trip during overloads. Many carriers won't write a policy until the panel is replaced. If you're buying an older home, a pre-purchase inspection that specifically checks for these panels can prevent a coverage gap on day one.
Polybutylene plumbing
Installed widely from the mid-1970s through the mid-1990s, polybutylene pipes were involved in class-action litigation because they fail without warning. Some carriers exclude water damage from poly-b failures or decline the risk entirely. If your home has it, replacement is usually the only path to standard coverage.
Oil-fired heating systems
Older Ohio homes often have oil boilers or oil furnaces with underground or basement storage tanks. Carriers ask about tank age and condition. A leaking underground tank can create an environmental liability that goes well beyond a standard homeowners claim.
Ordinance or law coverage: why it matters more in older homes
Ordinance or law coverage is an endorsement most homeowners have never heard of, but it's especially important for older properties. It pays for the additional cost of bringing your home up to current building codes during a repair or rebuild after a covered loss.
Say a kitchen fire causes $40,000 in damage to a 1955 ranch home. When the contractor opens the walls to repair the damage, they discover the electrical needs to be brought up to current code, the insulation must meet modern standards, and the HVAC ductwork must comply with today's energy efficiency requirements. Without ordinance or law coverage, you pay those upgrade costs out of pocket. With it, your policy covers them up to the endorsement limit.
In Ohio, building codes have changed significantly over the decades. A partial loss on an older home can trigger far more code-compliance costs than the same loss on a newer build. Most standard homeowners policies do not include this coverage automatically, but it's available as an endorsement and it's relatively inexpensive for what it provides.
Wind and hail in northwest and central Ohio
Ohio is not a coastal state, but northwest and central Ohio take a real beating from spring and summer storms. Hail that would dent a new composite shingle roof can shatter original slate tiles or split wood shakes. Wind-driven rain finds its way into older window frames and aging caulking in ways it wouldn't with modern construction.
It's worth knowing how your deductible applies to wind and hail claims specifically. Ohio carriers have been increasingly writing separate wind and hail deductibles, often expressed as a percentage of the home's insured value rather than a flat dollar amount. On a $300,000 replacement cost policy, a 1% wind and hail deductible means you pay the first $3,000 out of pocket. Our post on Ohio wind and hail deductibles breaks down exactly how this works and what to look for on your declarations page.
For older homes with more vulnerable exteriors, keeping documentation of roof condition, photos of the home's exterior, and records of any repairs is smart practice. It makes the claims process smoother and can help when a carrier questions whether damage is from a storm or from pre-existing wear.
What to expect when shopping for coverage
Shopping home insurance for an older Ohio home is a different experience than buying coverage for a newer build. A few things to expect:
- Inspection requirements. Many carriers require an inspection before binding or within 60 days of binding coverage on an older home. This usually involves an exterior inspection, sometimes interior. If the inspector finds issues, the carrier may require remediation before renewing.
- Fewer carrier options. Not every carrier will write homes over a certain age or with certain systems in place. An independent agency like Ley Insurance has access to multiple markets and can find carriers that specialize in older homes when the standard market won't take the risk.
- Higher premiums. Expect to pay more per $1,000 of insured value on an older home than on a newer one. The exposure is real and the pricing reflects it. That said, there's variation between carriers, and working with someone who shops the market on your behalf matters.
- Coverage exclusions to watch for. Review your policy for exclusions specific to older home components. Some policies exclude foundation issues, plumbing failure from certain materials, or collapse of structures that were not in a state of sudden and unexpected failure. Read the exclusions section carefully.
If you're unsure how your current coverage compares to what you actually need, a policy review is a good first step. Our post on what drives homeowners insurance costs in Ohio gives useful context on how the variables stack up.
Practical steps to protect your older home and your coverage
Owning an older home doesn't mean you're stuck with bad coverage or high premiums. There are real things you can do to improve both:
- Update the electrical panel. Replacing a Federal Pacific or Zinsco panel with a modern breaker panel opens up more carrier options and can reduce your premium. The cost is typically $1,500 to $3,000, and the insurance savings over time often justify it.
- Document the home thoroughly. Photos of every room, the roof, the foundation, mechanical systems, and any unique architectural features. Store copies offsite or in the cloud. This documentation supports a replacement cost claim and helps an adjuster understand what was there before a loss.
- Get a current appraisal. A certified appraisal that specifically addresses replacement cost for older construction gives you and your agent a solid number to anchor coverage to.
- Add ordinance or law coverage. As discussed above, this is one of the most underused endorsements for older homes and one of the most useful.
- Review your policy annually. Inflation affects construction costs, and your coverage limit should keep pace. A home that was adequately insured five years ago may be underinsured today.
Ready to review your older home coverage in Ohio?
Ley Insurance Agency is an independent agency serving homeowners across northwest and central Ohio, including Lima, Findlay, Defiance, Van Wert, Piqua, and the surrounding communities. Because we work with multiple carriers rather than representing just one, we can shop the market to find coverage that actually fits an older home, including specialty markets when the standard market steps away.
If you're insuring a home with original character and real age behind it, don't settle for a policy built for a cookie-cutter subdivision house. Give us a call at (419) 222-2454 or reach out through our contact page to start a conversation. We'll look at what you have, explain what you may be missing, and help you get coverage that's built for the home you actually own.
Get A Quote
At Ley Insurance Agency, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact Ley Insurance Agency
Recent Posts